Zoome Withdrawals in Australia: Limits, KYC and Timing
 Available in AU
Zoome’s current terms set the minimum fiat withdrawal for AUD at A$75. Standard withdrawal-frequency limits are A$1,500 per day, A$7,500 per rolling seven-day period and A$15,000 per month. Those are the clearest numbers to use when planning a cashout, although the maximum for an individual payment method can still be lower and is shown in the cashier.
The less certain part is timing. Zoome’s FAQ says withdrawal requests take no more than 24 hours on the casino side and that many are completed within three hours, while the current Terms say the operator aims to process requests within 72 hours after approval. Because those two official statements do not match, it is more useful to treat them as separate expectations rather than promise one exact Zoome withdrawal time.
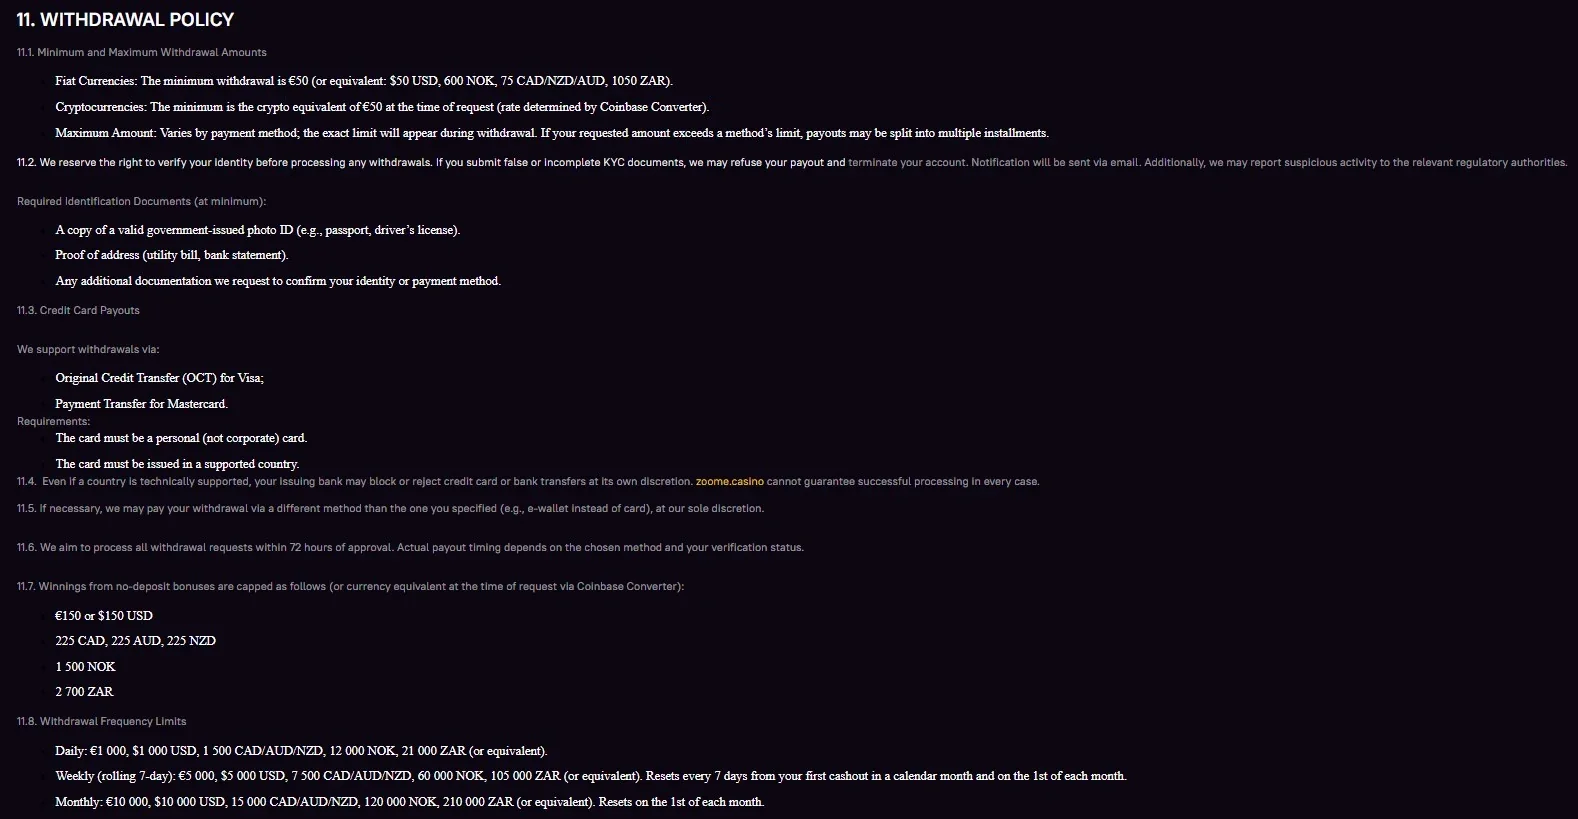
Table of Contents
- Zoome withdrawal limits in AUD
- Why the withdrawal-time answer is not one number
- KYC can pause a cashout
- The three-times deposit wagering rule
- Withdrawal methods and the deposit-method connection
- Fees: casino fee versus provider fee
- What to check before requesting a payout
- What if a withdrawal remains unresolved?
- Three common cashout scenarios
- How to diagnose a delayed withdrawal
- A smoother path from request to payout
Zoome withdrawal limits in AUD
The standard AUD limits are straightforward once separated by period. The daily ceiling is A$1,500, the rolling weekly ceiling is A$7,500, and the monthly ceiling is A$15,000. Progressive jackpot winnings are treated separately in the current Terms and are not included in those standard frequency limits.
| Withdrawal rule | Current AUD amount | What it means |
|---|---|---|
| Minimum fiat withdrawal | A$75 | A fiat cashout below this amount does not meet the published minimum. |
| Daily standard limit | A$1,500 | The normal daily withdrawal ceiling before method-specific restrictions. |
| Rolling seven-day limit | A$7,500 | A weekly frequency limit measured across the applicable rolling period. |
| Monthly limit | A$15,000 | The standard monthly ceiling stated for AUD. |
These figures are standard account limits, not a guarantee that every payment option will accept the full amount in one transaction. Zoome also says the maximum can vary by method and that the exact method limit is displayed when a withdrawal is requested. If the method limit is lower than the account-level ceiling, the cashier figure is the practical constraint for that request.
Why the withdrawal-time answer is not one number
Zoome currently publishes two different processing expectations. Its FAQ says the maximum processing time on its side is 24 hours and that most requests are completed within three hours. The Terms use broader wording and say the casino aims to process withdrawal requests within 72 hours of approval. Those statements describe the same general stage differently, so quoting only the faster figure would create a misleading impression of certainty.
There is also a distinction between internal processing and the time it takes money to arrive after the operator releases it. A request can move through account checks, payment approval and then the external payment network. Zoome’s Terms specifically say actual payout timing depends on the chosen method and verification status. Bank-transfer wording also refers to processing within three business days, while banks and intermediaries can add their own handling time.
For planning purposes, separate the journey into three stages: request submitted, request approved and processed by Zoome, and funds settled by the bank, card network, wallet or crypto network. The official material supports that staged view, but it does not support one universal arrival time for every Australian account and every method.
KYC can pause a cashout
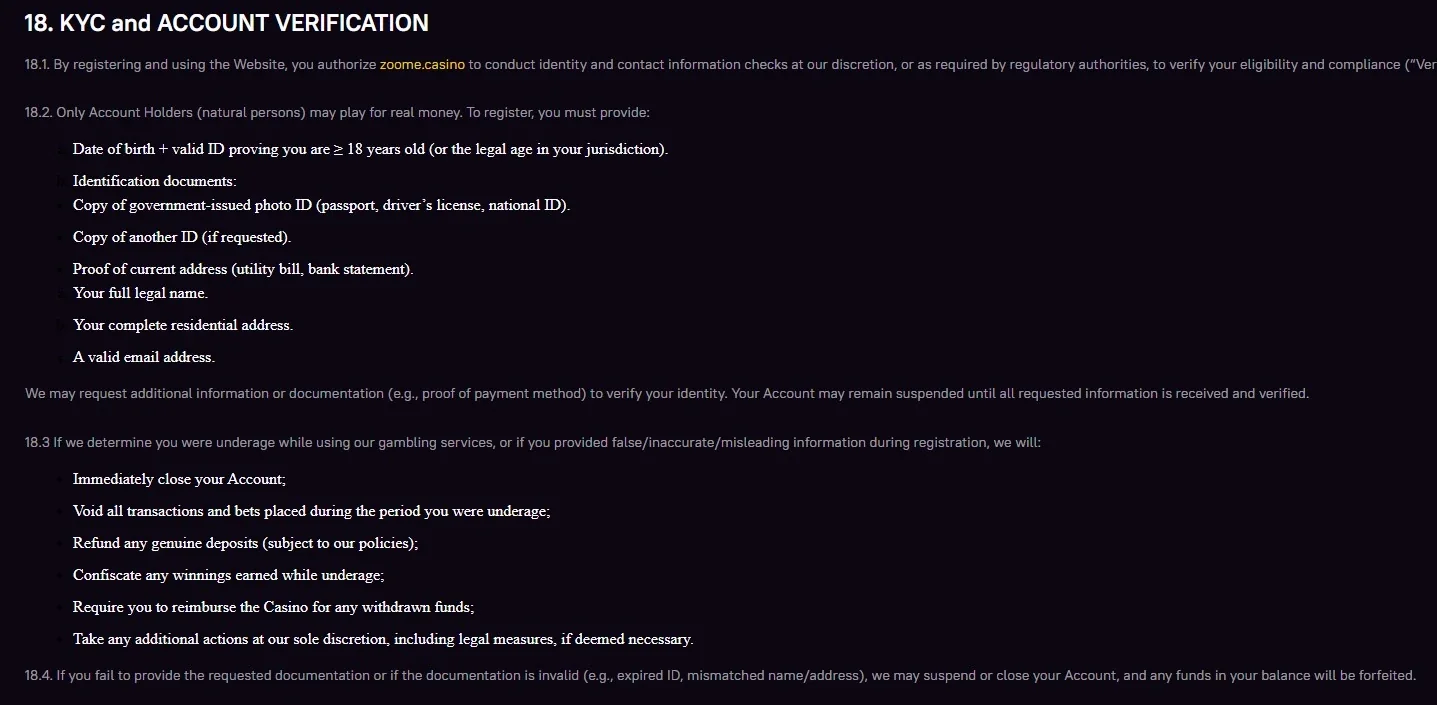
Zoome can request identity verification before processing a withdrawal. The current Terms list identity and address evidence among the documents it can request, and the FAQ also warns that a verification request can delay a cashout. That means an account that has deposited and played normally can still be asked to complete checks when withdrawing.
This is best treated as a preparation issue rather than an unexpected exception. Account details should match the identity and payment information used on the site, and requested documents should be current and readable. A mismatch in name, address or payment ownership can extend the review or lead to a rejected request.
For the full document list and verification workflow, see the KYC requirements. For the account-creation steps that come before verification, see account setup. Verification status is part of the cashout timeline and can be required before funds are released.
The three-times deposit wagering rule
Zoome’s Terms require deposited funds to be wagered three times before those funds can be withdrawn. This is separate from bonus wagering. It applies to the deposit itself and is relevant even when a player is not using a welcome offer or other promotion.
A simple example shows the difference. If an account deposits A$100, the published rule requires A$300 in qualifying wagering before that deposit can be withdrawn. If several deposits are made without gameplay, the Terms say the combined deposits must be wagered before a withdrawal is initiated. This requirement should be checked before assuming a cashout problem is caused by KYC or a payment method.
An active bonus can create another layer because bonus terms may have their own wagering conditions. If a withdrawal is unavailable, review the real-money deposit turnover and any active promotion separately. Active promotional wagering requirements can therefore affect whether a cashout is currently available.
Withdrawal methods and the deposit-method connection
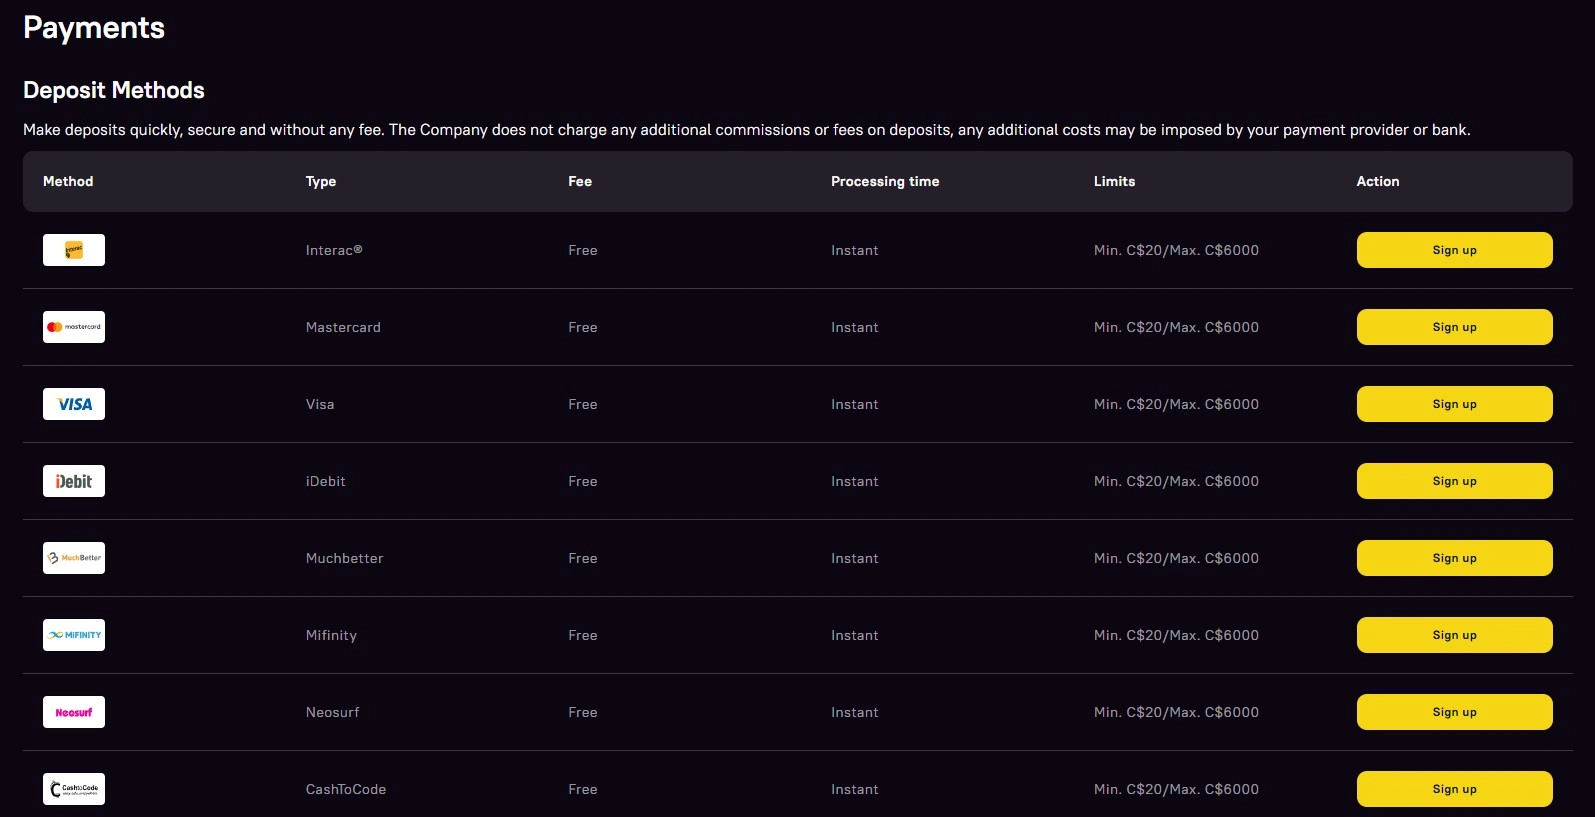
Zoome’s FAQ says withdrawals are available through payment methods that have previously been used for deposits. The Terms also describe card payouts through Visa Original Credit Transfer and Mastercard Payment Transfer where supported, while allowing the casino to use an alternative method when necessary. A card issuer or bank can still reject a transaction even when the method is technically supported.
That is why the practical method list should be taken from the logged-in cashier rather than a global payments page. The public payments page shows a broad set of cards, wallets and crypto options, but availability can differ by account and market. For the wider deposit and currency picture, see the payment methods.
Crypto withdrawals use exchange-rate-based limits rather than the fixed AUD ceilings displayed for fiat. Zoome’s Terms refer to Coinbase Converter for the crypto equivalent at the time of a request. Because crypto values change, a fixed coin amount should not be treated as permanent unless it is displayed in the current cashier.
Fees: casino fee versus provider fee
Zoome’s FAQ says the casino does not charge a platform fee for deposits or withdrawals. That does not mean every transfer is cost-free. The same guidance says a bank or payment provider can impose its own charges, and the Terms specifically mention possible intermediary-bank fees on bank transfers.
The useful question is therefore not simply “Is the withdrawal free?” but “Who may charge for this route?” A zero casino fee can coexist with an issuer fee, intermediary-bank charge, wallet fee, crypto network cost or currency-related adjustment. If the cashier shows a charge, compare it with the terms for the specific payment provider before confirming the request.
Zoome’s operating currency is EUR even though AUD is accepted. Its Terms note that transactions in another currency can differ slightly because of bank and processing-system conversion rates. That is another reason to distinguish a platform fee from exchange-rate effects or third-party charges.
What to check before requesting a payout
- Confirm the withdrawal is at least A$75.
- Check that the request fits the daily, rolling weekly and monthly limits.
- Review the cashier’s method-specific maximum before entering the amount.
- Make sure the deposit wagering requirement has been completed.
- Check whether an active bonus has unfinished wagering.
- Use payment and account details that match the account holder.
- Be prepared to complete KYC if the account is selected for verification.
If a cashout is rejected, Zoome’s FAQ tells users to check the email associated with the account for instructions from the finance team. A rejection does not automatically mean the funds are lost; it can reflect incomplete verification, incorrect bank information, active wagering or a method limit.
What if a withdrawal remains unresolved?
Start with Zoome support and keep a record of the request, transaction details and any verification correspondence. If the issue becomes a formal dispute, Zoome’s current Terms name EGIS as an independent ADR escalation route under the operator’s Tobique framework. That is not an Australian local dispute scheme.
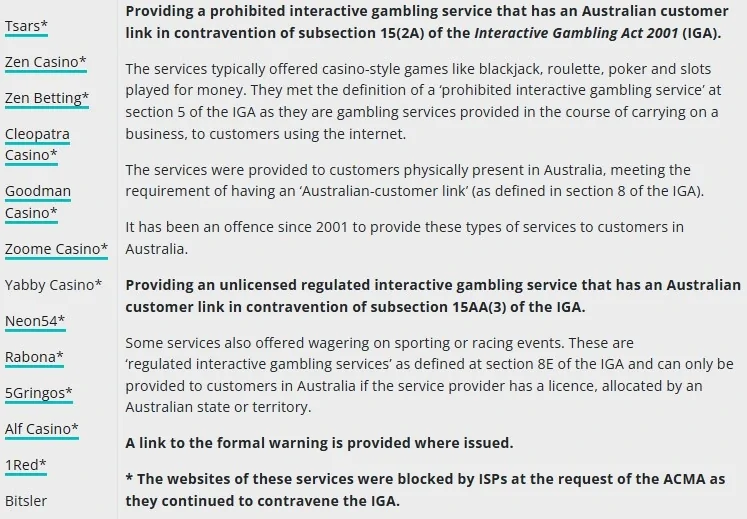
The trust and regulation information explains the operator licence, Australian ACMA history and the distinction between offshore operator arrangements and Australian regulation. For the full operator overview, return to the full Australia review.
Three common cashout scenarios
Scenario 1: A$500 withdrawal. This is above the A$75 minimum and below the standard A$1,500 daily ceiling. If the method shown in the cashier allows A$500, the next questions are whether deposit wagering is complete and whether verification has been requested. The daily limit alone would not be the obstacle.
Scenario 2: A$2,000 withdrawal in one day. The standard daily ceiling is A$1,500, so the full amount does not fit the published daily frequency limit. A player should not assume the request will simply be paid in full because the monthly limit is higher. Daily, weekly and monthly limits operate together, and method-specific limits can be tighter still.
Scenario 3: several withdrawals across a week. Five A$1,500 withdrawals would total A$7,500, which reaches the standard rolling seven-day ceiling. Another request inside that period can therefore be affected even if it is below the daily limit. Tracking cumulative withdrawals matters when several smaller cashouts are used instead of one large request.
These examples are useful because they separate account-level limits from processing speed. A request can fit every published amount limit and still take longer because of KYC, payment routing or provider settlement. Conversely, a fast payment method does not override the account’s withdrawal-frequency ceilings.
How to diagnose a delayed withdrawal
If a payout has not moved as expected, check the causes in a logical order. First confirm that the request is still inside the cashier and has not been rejected by email. Then check unfinished bonus wagering and the three-times deposit rule. After that, look for any verification request or missing document notice. Finally, consider whether the payment provider or bank is still handling a transaction that Zoome has already approved.
This order helps avoid treating every delay as the same problem. A pending KYC review, a declined bank transfer and an exceeded method limit require different actions. Zoome’s FAQ also notes that incorrect bank details, an active bonus and a selected-method limit are common reasons a withdrawal can fail. Keeping those categories separate makes support correspondence more specific and easier to resolve.
A smoother path from request to payout
For an Australian account, the most useful fixed figures are A$75 minimum, A$1,500 daily, A$7,500 per rolling week and A$15,000 per month. KYC and the three-times deposit wagering rule can affect whether a request is processed, while payment-provider restrictions can affect how the payout is routed.
Timing deserves more caution than the limits. Zoome currently publishes a 24-hour maximum on its FAQ but a 72-hour processing aim in its Terms, so neither should be presented as a guaranteed universal payout time. Check the cashier and account status for the specific request rather than relying on a single headline speed.
Published by the Zoome Casino team.